

I am pricing two deals in the Midwest as I write this. While I do it, a CRA rule change is moving through Washington that I cannot stop thinking about, because it reaches straight into the math on my screen.
Let me explain it the way I wish someone had explained it to me.
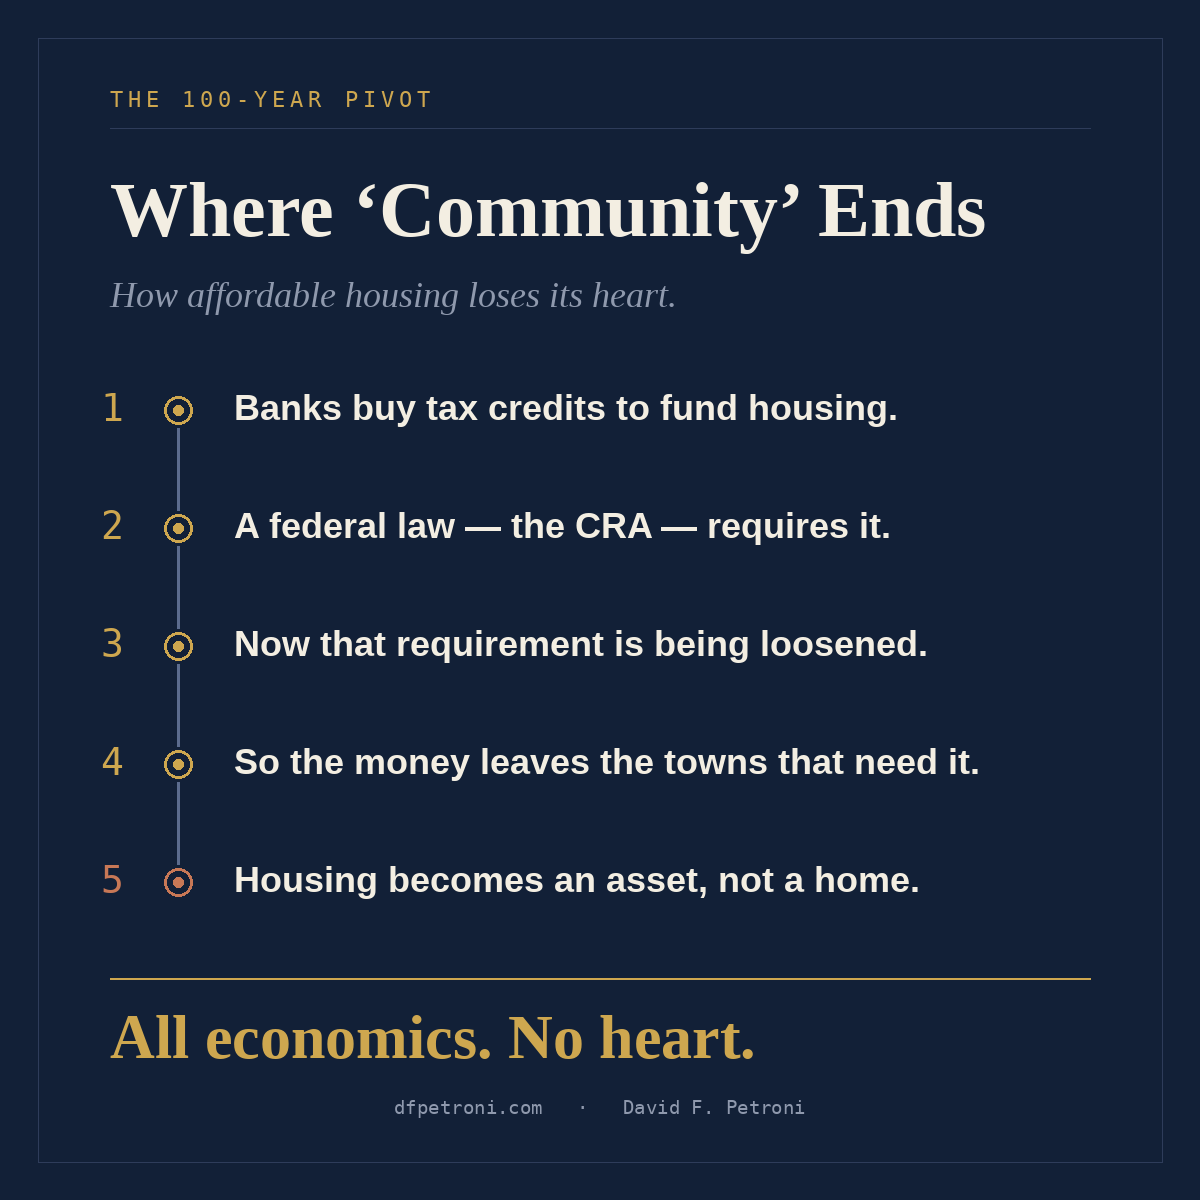
The CRA Rule Change Nobody Reads
Almost every affordable housing deal in this country runs on bank money. Banks buy the tax credits that turn a set of drawings into a building. The reason they show up is a law called the Community Reinvestment Act. Congress passed it in 1977, after redlining, to push banks to invest in the same neighborhoods they take deposits from. The version we actually work under, the one with the tests and the grades, was written in 1995.
The simple math
A bank’s record gets graded on a clock. For most of my career that clock ran about every three years. Picture a bank that puts a million dollars into a city like Cincinnati. Examiners every three years means roughly three hundred thousand dollars a year of steady pressure to keep that money in the neighborhood.
Now change two things at once, which is what is happening. Ask for a little less, and stretch the time between exams toward five years. The same commitment is suddenly under two hundred thousand a year, with longer stretches when no one is looking. Same bank. Same city. A little more than half the yearly effort.
And watch who gets that break. The lighter exam schedule now reaches banks holding up to thirty billion dollars in assets. Thirty billion. We are calling those community banks. They are not the bank on the corner of a town square. The label just lets them be treated like one.
What it looks like in real money
Round numbers make a point, so let me use a real one.
The largest bank based in Cincinnati once promised about thirty billion dollars to communities over five years. Around nine billion of that was the community development piece, the part closest to affordable housing. Call it a little under two billion dollars a year, from one bank, in one footprint. That is what the old pressure could move.
Now soften the yardstick that measured it. Shave even ten percent and you have pulled close to a billion dollars out of community development over five years, from a single bank. Ten percent is a polite number. I think the real one runs higher.
Who this lands on
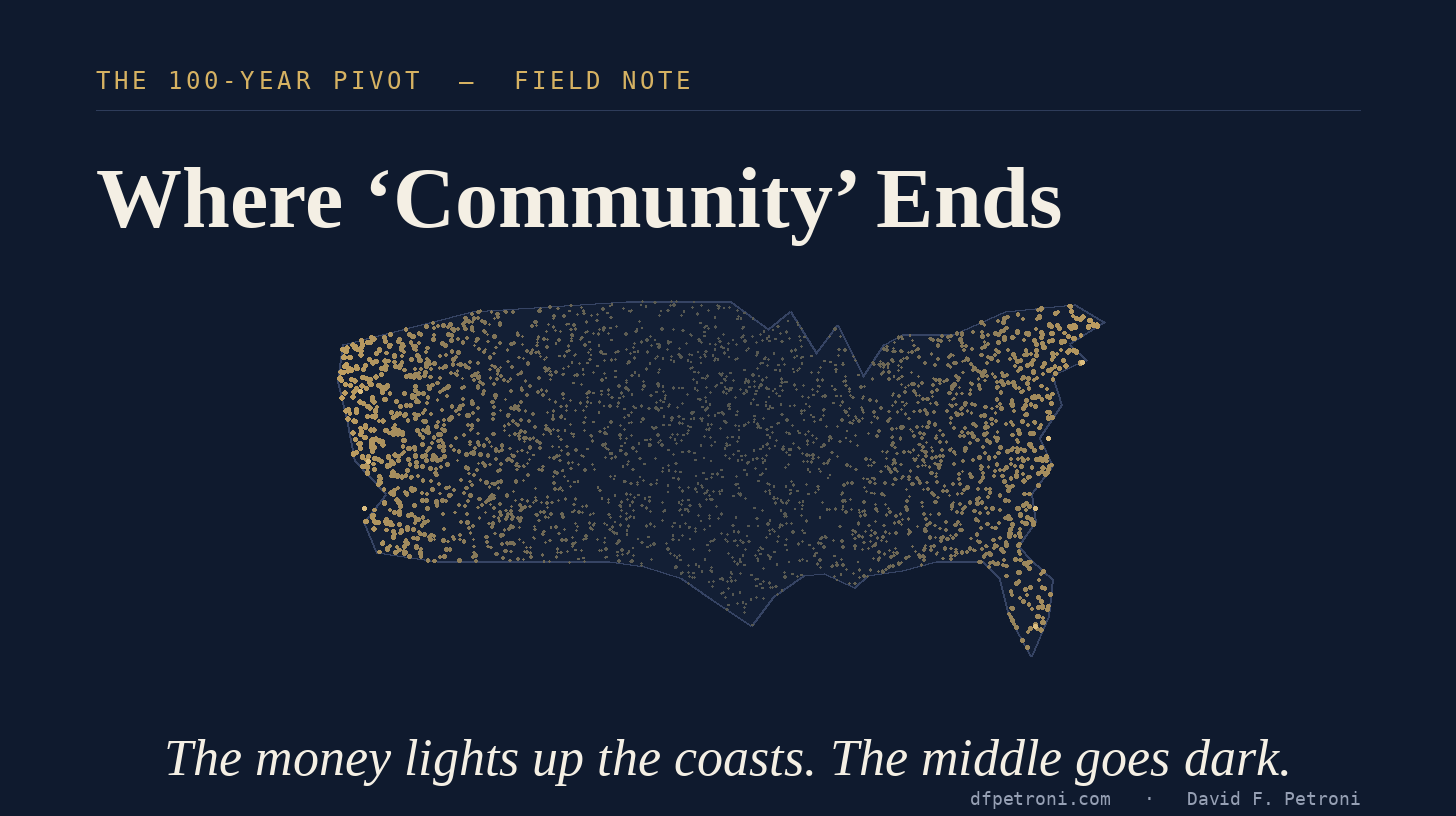
The money does not pull back evenly. It stays comfortable on the coasts and in the strong markets that already price tight. The places left waiting are the small cities and the rural counties, the rust belt, the middle of the country that does most of the work and draws the least of the capital.
We are doing all of this in the middle of a housing shortage that is not subtle. The country is short more than seven million homes its lowest income families can actually afford. We are loosening the one rule that aimed private money at that gap, at the moment the gap is the widest it has ever been.
Community, or economics
I want to be fair to the banks asking for this. They are not villains, and I need them. The people inside them are my colleagues, and many are my friends. The rules are complicated and changed more than once in a few years, and following them costs real money. If I ran a bank I would probably ask for relief too.
But I keep turning over one question. When a bank reaches for the parts of a deal that throw off fees and lets go of the long commitment, when it takes the relief and keeps the deposits, is this about the community, or is it about the economics?
I think I know the answer. I think we are about to find it out the hard way.
I could be wrong about how much it hurts, and I hope I am. In The 100-Year Pivot I call this compliance drift, the slow way a law keeps saying serve the whole community while the rules quietly redraw where the community ends.
If you work in this world, tell me what you are seeing on your deals. I would rather learn from your read than be proven right.
Notes
- CRA was enacted in 1977; the exam framework we work under came with the 1995 overhaul, which regulators have proposed reverting to. (Federal Reserve History; Minneapolis Fed)
- The OCC has examined banks roughly every three to four years; in 2025 it extended the maximum gap to 78 months for well rated banks holding up to thirty billion dollars in assets. (OCC Bulletin 2025-24; Troutman Pepper)
- The agencies proposed rescinding the 2023 CRA rule for the lighter 1995 framework, dropping the 2023 community development benchmarks. How the two moves add up is my read. (Federal Reserve, July 2025)
- The largest Cincinnati based bank announced a roughly thirty billion dollar, five year community plan, about nine billion of it community development; it now holds more than two hundred ten billion dollars in assets. Figures rounded. (NCRC; SEC filings)
- The ten percent and the dollar effect are my illustration of direction, not a figure set by any rule.
- National Low Income Housing Coalition, The Gap 2026: a shortage of about 7.2 million affordable homes for the lowest income renters.
Working an affordable housing deal?
Get a Subsidy Layering Review | See All Services | Get in Touch